Skip to content

Case study

635B Senja Road to Copen Grand: buying an EC while still living in the HDB flat

Many HDB owners assume moving to an EC needs a lot of cash saved first. My clients bought at Copen Grand under the Deferred Payment Scheme with an EC bridging loan, so they could keep living at 635B Senja Road. The catch was the timeline: the flat had to be sold in time to repay the bridging loan.

Published
19 Oct 2026
Reading time
3 min
Property
HDB flat, 635B Senja Road, Bukit Panjang; next home an executive condominium at Copen Grand, Tengah

Filed underHDB resaleNew launch

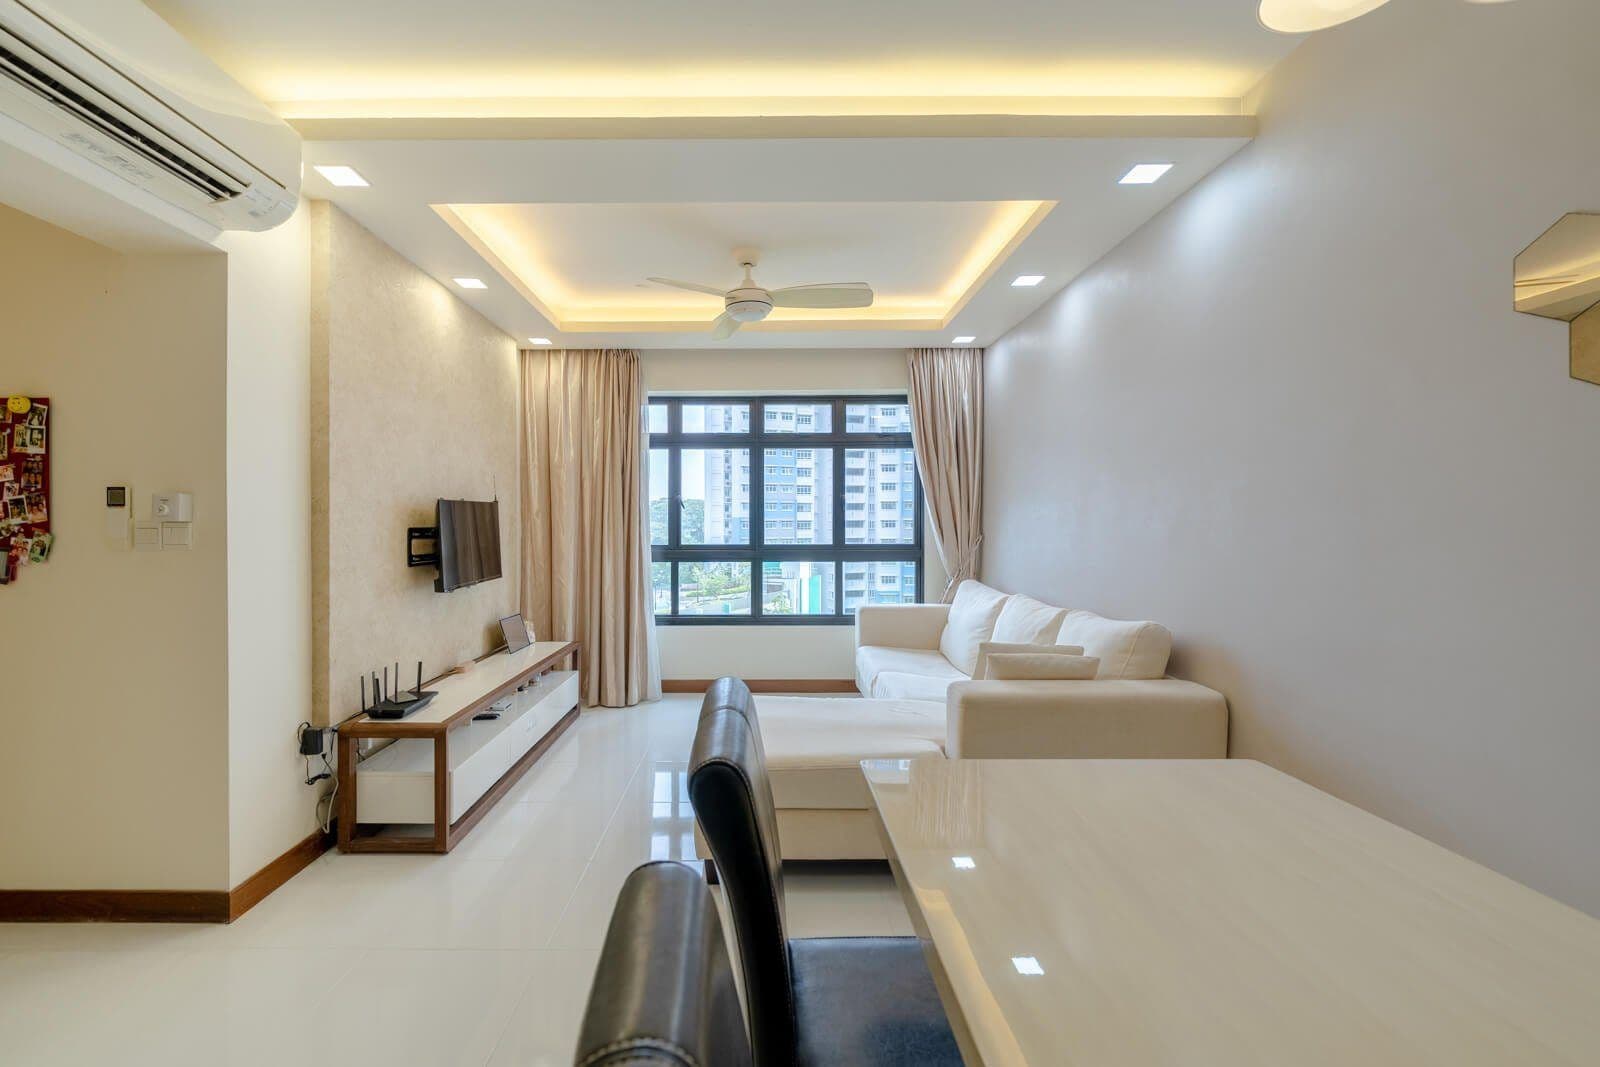
Living room of the flat at 635B Senja Road that the family sold
Living room of the flat at 635B Senja Road that the family sold. Photograph from the team’s listing.

Key takeaways

  • The clients bought an EC at Copen Grand under the Deferred Payment Scheme with an EC bridging loan, and kept living in their HDB flat at 635B Senja Road while it was built.
  • The flat then had to be sold in time to repay the bridging loan, and HDB requires an EC buyer's flat to be disposed of within six months of key collection.
  • The resale application went in before the EC's TOP; resale completion was deferred by agreement, and HDB approved a three-month extension of stay after TOP. This was case-specific coordination, not a standard entitlement.
  • S$642,000 was the sale price after a January 2025 option; S$530,000 was HDB's November 2022 valuation. The gap is not a profit or a same-date premium.

The property

My clients owned an HDB flat at Block 635B Senja Road in Bukit Panjang. They bought a unit at Copen Grand, an executive condominium in Tengah, under the developer's Deferred Payment Scheme, and took an EC bridging loan.

The bridging loan let them keep living in their flat while Copen Grand was being built, instead of selling it first. It also set a timeline: the flat had to be sold so that the bridging loan could be repaid.

Separately, HDB requires an EC buyer who owns an HDB flat to dispose of it within six months of collecting the EC's keys.

What the client wanted

To buy an executive condominium at Copen Grand without selling their HDB flat first, keep living in the flat while the EC was built, and then sell it in time to repay the EC bridging loan.

The challenge

So the sale had to meet the bridging loan's timeline, while the family still needed somewhere to live until Copen Grand was ready.

The usual order did not fit. HDB's temporary extension of stay, which lets sellers remain in the flat for up to three months after the sale completes, is meant for sellers who have already bought a completed home. HDB's terms say the property bought must be "completed and ready for occupation", and the request goes in with the resale application.

When the resale application was due, Copen Grand had not yet obtained its TOP. Selling too early risked leaving the family without a home; selling too late risked missing the bridging loan's timeline.
James's view

My assessment

Many HDB owners know or have heard of a neighbour who moved from an HDB flat to an EC, but never knew it was possible for them. Many think it needs a lot of cash savings. That is not entirely true. There are funding requirements, but many sellers do not know how to use the options available, such as buying under a Deferred Payment Scheme with an EC bridging loan.

The options only help if the timeline is planned. My view was that this could only work if every party agreed the timing before the option was signed, not after. The buyers of the flat had to be comfortable with a later completion and, after that, a short extension of stay. If any one stage moved, the plan would have needed to change, so nothing was left to be worked out along the way.

Evidence

What the records show

HDB's Terms and Conditions for Temporary Extension of Stay (updated 19 February 2026) say the property bought must be "completed and ready for occupation, i.e. not in the process of construction", that the request is submitted with the resale application, and that the extension may not run beyond three months from resale completion. HDB's conditions for EC buyers require an HDB flat to be disposed of within six months of collecting the EC's keys.

CDL's construction page (updated 19 October 2026) records Copen Grand's TOP as obtained in April 2025.

The strategy

The bridging loan's timeline set when the flat had to be sold. I set out the stages in order and agreed them with the buyers before the option: when the resale application would be submitted, a completion date later than the earliest one HDB would offer, and a temporary extension of stay after completion.

HDB's own process allows two of these by agreement. The option to purchase lets the seller and the buyers agree when the resale application is submitted, and HDB says the completion date in its acceptance letter is the earliest possible date; both parties may agree a later one.

Timeline

  1. Stage 1

    EC booked

    The clients booked a unit at Copen Grand under the developer's Deferred Payment Scheme. HDB's valuation of the flat, assessed in November 2022 during the booking, was S$530,000.

  2. Stage 2

    Option granted

    The flat was optioned out on 29 January 2025, with the timing of the later stages agreed with the buyers in advance.

  3. Stage 3

    Resale application

    Submitted about 60 days after the option was exercised, before Copen Grand obtained its TOP.

  4. Stage 4

    Deferred completion

    Resale completion was set later than the earliest date, by agreement with the buyers.

  5. Stage 5

    EC TOP

    Copen Grand obtained its TOP. CDL's construction page records it as obtained in April 2025.

  6. Stage 6

    Extension of stay

    HDB approved a three-month temporary extension of stay after resale completion.

The result

The flat was sold for S$642,000.

Two figures are easy to misread here. S$530,000 was HDB's valuation, assessed in November 2022 when Copen Grand was booked; S$642,000 was the price the flat later sold for, after it was optioned out in January 2025. The S$112,000 between them is not a profit or a return, because it does not take away the loan, the CPF refund with accrued interest or the costs of selling, and it is not a premium over a valuation on the same date: the two figures were set more than two years apart.

James's view

Why I think it worked

The Deferred Payment Scheme and the bridging loan let the family buy first and stay in their flat while the EC was built. Then every stage of the sale was agreed before it was needed, with buyers who understood the timing and HDB's process followed at each step. The order was unusual; the coordination was what made it hold together.

What others can take from this

  • Moving from an HDB flat to an EC does not always mean selling first or having a lot of cash saved. Ask what options, such as a Deferred Payment Scheme and a bridging loan, apply to you.
  • A bridging loan comes with its own repayment timeline. Know it from your bank before you set the timing of the sale.
  • HDB's current terms allow an extension of stay only when the home you have bought is completed. The approval in this case was exceptional: do not plan around one for a home still being built.
  • Agree the timing with the buyers before the option is signed, not after.

Planning a similar move? Buying an EC before selling your HDB sets out how the flat's value, bridging finance and the dates fit together; NPS and DPS compared explains the payment schemes; and Solano Grand at Senja Close covers what is known about the next EC in Bukit Panjang. This case records one household's move. It does not mean another household, or a future launch, will get the same financing, the same timeline or the same approvals.

Every property and owner is different. This outcome depended on the conditions described and should not be read as a guaranteed result for another sale or purchase. Details are anonymised unless the client gave written consent.

Sources

  1. 1.
    Terms and Conditions for Temporary Extension of Stay

    Housing & Development Board · Period: Updated on 19 Feb 2026 · Extracted 19 Oct 2026

    Completed property, timing of the request, three-month limit, buyers' agreement and HDB approval.

  2. 2.
    Selling a flat: eligibility, Option to Purchase, resale application and completion

    Housing & Development Board · Period: Last updated 7 Sep 2026 · Extracted 19 Oct 2026

    Clause 12 of the option; completion later than the earliest date by mutual agreement.

  3. 3.
    Conditions After Buying an Executive Condominium

    Housing & Development Board · Period: Last updated 28 Jul 2026 · Extracted 19 Oct 2026

    Disposal of an HDB flat within six months of EC key collection.

  4. 4.
    Construction & TOP Progress

    CDL Homes · Period: Updated as at 19 Oct 2026 · Extracted 19 Oct 2026

    Copen Grand: TOP obtained in April 2025.

General information only, not financial, legal or tax advice. Figures reflect the data period shown and may since have changed; your own circumstances will differ. Full disclaimer.

Talk to James

Considering a similar move? Discuss which financing and timing options may apply to you.

Every household's loan, sale and dates are different. James can go through which options may apply to yours. Please do not send NRIC, income, CPF or bank documents through the form or WhatsApp.

Your WhatsApp message will read: “Hi James, I read "635B Senja Road to Copen Grand:…" on JamesWongHomes.com and would like to discuss a similar HDB-to-EC move. [635b-senja-road-to-copen-grand-ec-bridging-loan]” Edit it before you send.

Prefer to call? +65 9696 9567

I usually reply within one working day.

Messages go directly to James. Your details are used only to respond to your enquiry. See the privacy notice.