Decision guide · HDB upgrader
Own a Woodlands HDB flat and eyeing Wynwood Grand? Your move starts with your current flat
For Woodlands and Admiralty HDB owners: what your flat could sell for, what you'd actually walk away with after the loan and the CPF refund, and how to time the sale around an EC that's years from its keys. Updated 21 October 2026.
- Published
- 21 Oct 2026
- Last fact-checked
- 21 Oct 2026
- Reading time
- 5 min
- Next review
- 21 Dec 2026
Filed underWoodlandsHDB resaleFinancingNew launch
Quick answer
If you own an HDB flat, your Wynwood Grand budget starts with your flat, not CDL's price list. First find out what flats like yours have actually sold for nearby. Then work out what you'd walk away with once the loan is repaid and your CPF goes back to your account. Then decide when to sell: you can book the EC while you still own the flat, as long as you sell it within six months of getting the EC's keys.
Part of: Buying an EC before selling your HDB: how valuation, bridging finance and timing work together
The options at a glance
Option 1
Sell first
Once the sale completes you know exactly what you have, but you'll need somewhere to stay until the keys.
Option 2
Book first, sell later
Stay put while it's built, but pay the first instalments without the sale money.
Option 3
Get the numbers first
What flats like yours sold for, the loan and the CPF refund decide which route works.
Key takeaways
- Start with what flats like yours actually sold for: same type and size, similar age, nearby blocks. An asking price isn't a sale.
- The sale price isn't your budget: the loan is repaid, the CPF you used goes back to your account with interest (you can use it for the next home, but it isn't cash), and a second-timer may owe a resale levy.
- You can book Wynwood Grand while you still own your flat; HDB gives you six months from getting the EC's keys to sell it.
- With a loan still on your flat, the bank lends less for the EC, unless that loan is paid off or HDB has approved the sale before the EC loan is drawn.
- CDL is aiming to launch in early 2027, so there's time now to price your flat, talk to the bank and choose the order before booking.
This guide is for
- HDB owners in Woodlands and Admiralty thinking about Wynwood Grand
- Owners whose flat has passed its minimum occupation period
It is not for
- First-time buyers with no flat to sell: start with the first-timer's checklist instead
What you need to decide
- Your flat's type, size, floor and the year its lease started
- The loan left on it, and the CPF you've used plus interest (from your CPF statement)
- Whether the flat has passed its minimum occupation period
- Where you'd stay if you sell before the EC's keys
Step by step
- 1
What could your flat sell for?
Real sales nearby, not the town average
Start with what flats like yours have sold for in HDB's records: same type and size, similar age, nearby blocks, the last few months. Woodlands on HDB Research lists them, and your Home Report turns them into an estimate for your flat. It's an estimate, not a formal valuation or an offer.
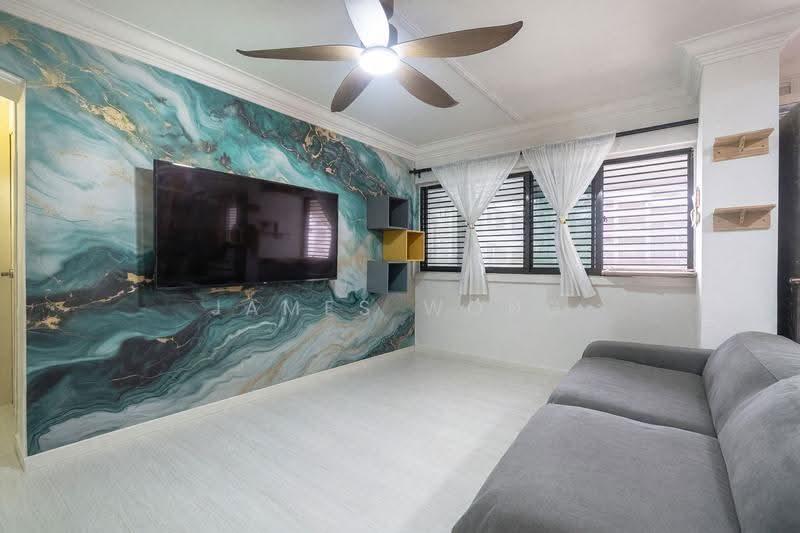
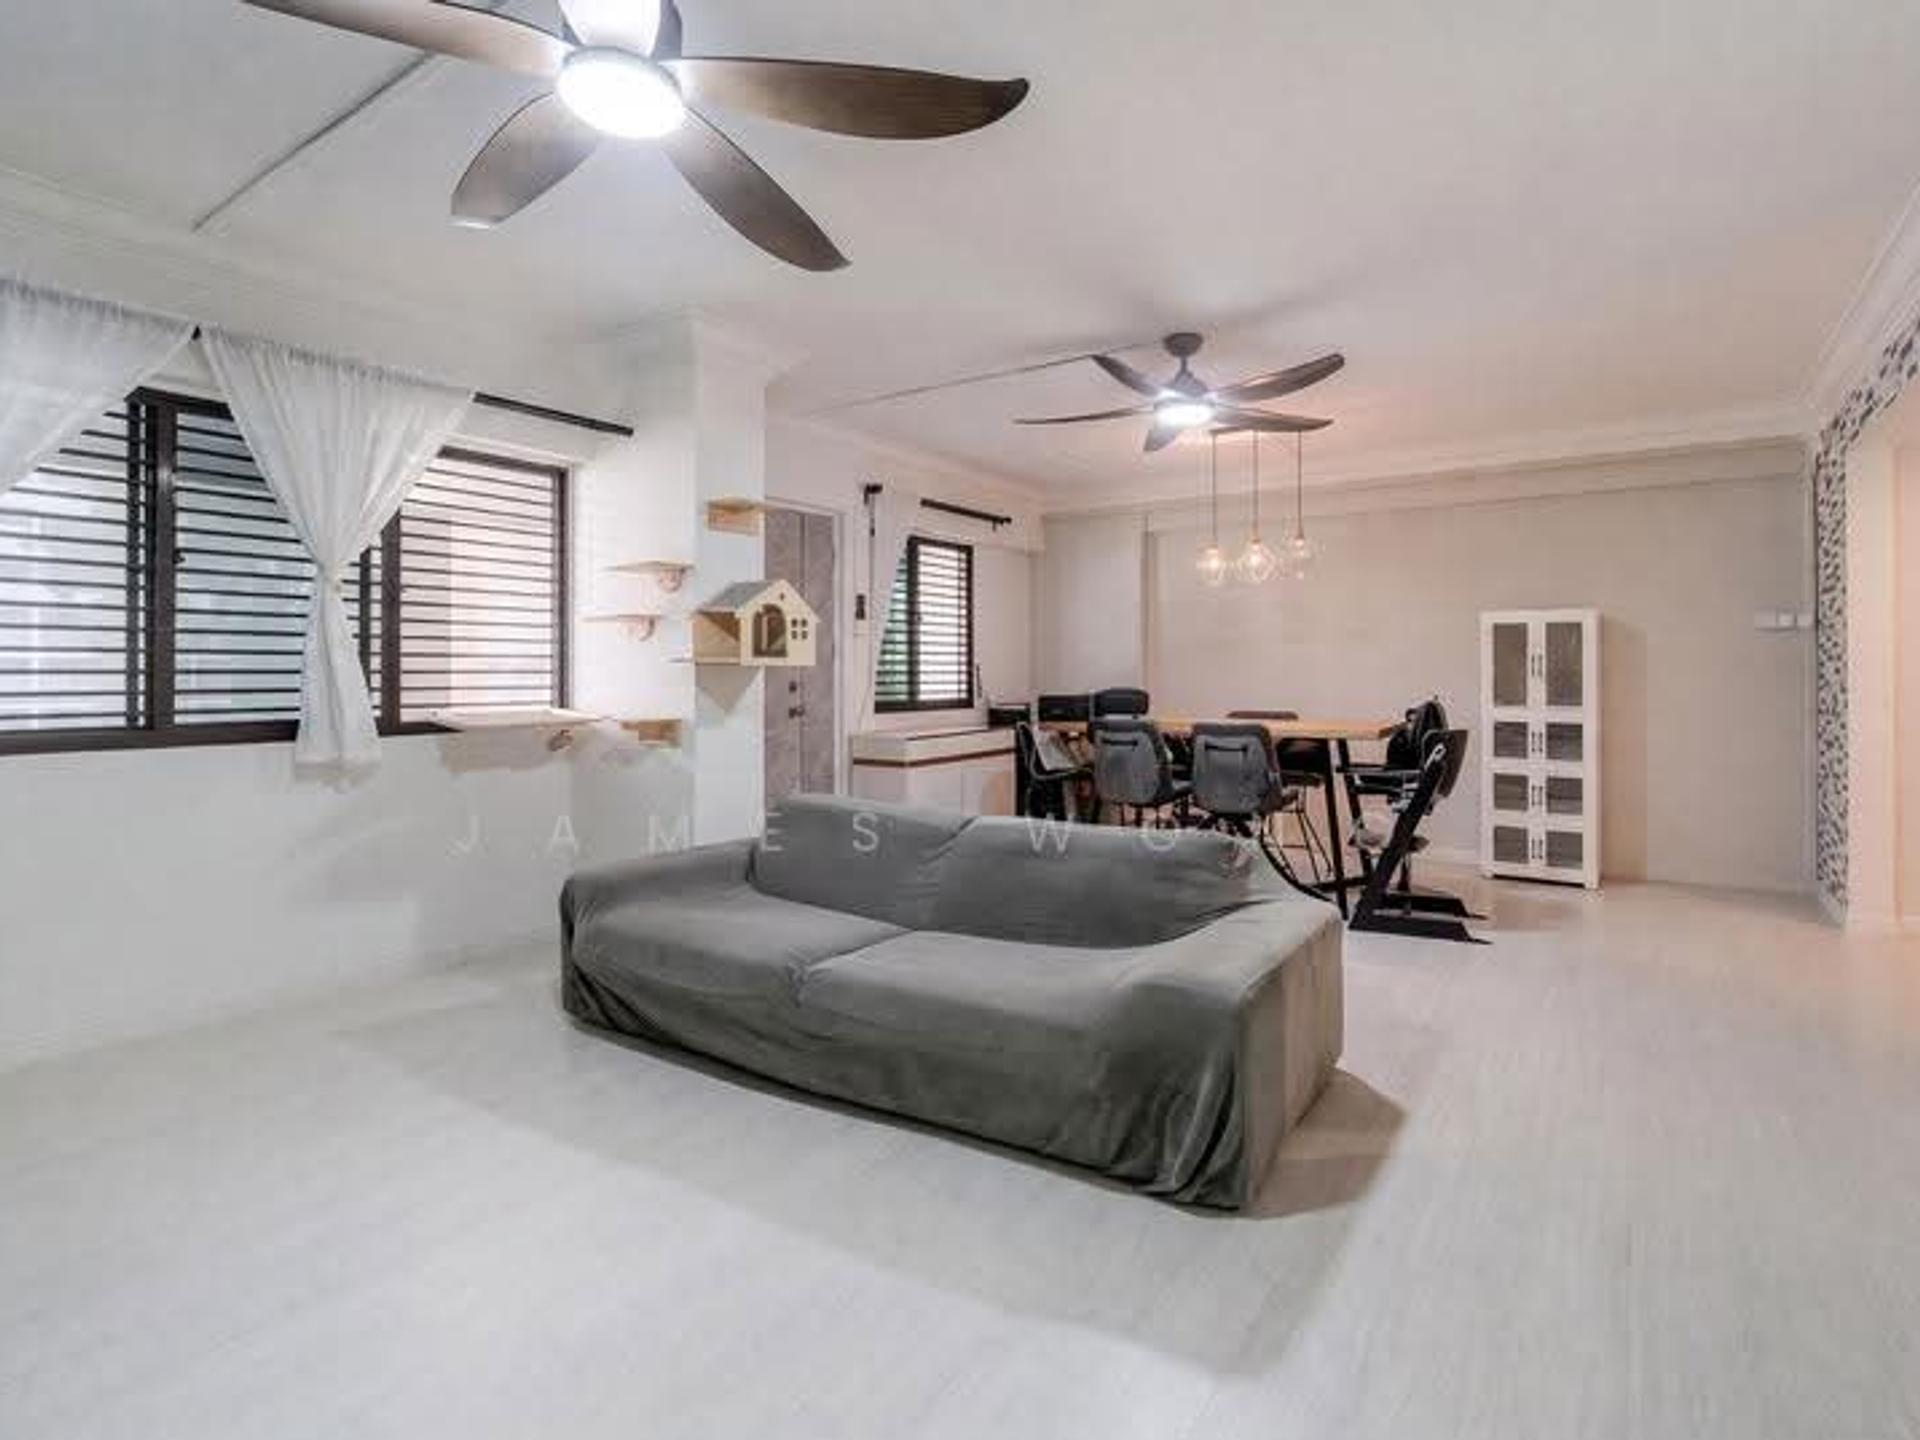
Here's an example from a flat James is selling now: 710 Woodlands Drive 70, a 101 sq m 4-room Model A with a lease from 1997, at an asking price of $588,000. That's what the owners are asking, not a valuation or a price already achieved. How James assesses that asking price against what nearby flats sold for shows the method: the nearby blocks first, then the block itself, then what the flat offers that the records can't show.
710 Woodlands Drive 70, the flat James is selling and this guide's pricing example. It is not linked to Wynwood Grand. · Photo: James Wong's listing - 2
What will you actually walk away with?
Cash in hand, and CPF back in your account
When your flat is sold, the loan is paid off first. Then the CPF you used for the flat, with the interest it would have earned and any housing grant, goes back into your CPF account. You can use it for your next home, but it isn't cash. A made-up example: sell for $560,000 with $120,000 left on the loan, $210,000 going back to CPF and $10,000 of costs, and you're left with $220,000 in cash plus the $210,000 in CPF.
If you bought your flat from HDB or with a CPF housing grant, you're a second-timer, and a resale levy may apply when you buy an EC from the developer. Set it aside from what the sale leaves. Who can buy a new EC explains the levy and the smaller grant.
The full working, why an estimate, the bank's valuation and HDB's valuation can differ, and what the bank looks at: buying an EC before selling your HDB flat.
Where a $560,000 sale goes: a made-up example
Assumed figures, not 710 Woodlands Drive 70's; your own loan statement and CPF Board's figures decide yours
Each bar is a part of the sale price: what repays the loan, what goes back to your CPF account, what is spent on costs, and the cash left. · $ · Example
- Sale price$560,000
- Repays the outstanding loan$120,000
- Back into your CPF account (not cash)$210,000
- Costs of selling (assumed)$10,000
- Cash left in hand$220,000
Part of the sale
Sale price $560,000; repays the loan $120,000; back into CPF $210,000; costs $10,000; cash left $220,000.
Source: Sales proceeds after selling your home (CPF Board), Last updated 30 Nov 2025. Extracted 20 Oct 2026.
$560,000 less $120,000 of loan, $210,000 back to CPF and $10,000 of costs leaves $220,000 in cash. The example assumes the flat was bought on the open market without a CPF housing grant, so no resale levy applies; if yours was bought from HDB or with a grant, a levy may apply when you buy an EC. Not a forecast of any price.
Show the data as a table
Where a $560,000 sale goes: a made-up example: data table Category Amount Sale price $560,000 Repays the outstanding loan $120,000 Back into your CPF account (not cash) $210,000 Costs of selling (assumed) $10,000 Cash left in hand $220,000 - 3
Sell first, or book first?
Both can work; your dates decide
Sell first and, once the sale completes, you'll know exactly what you have before you book, and with the flat's loan gone the bank treats the EC loan as your only one. The catch: you need somewhere to stay until the EC is ready, which is years after the launch. Book first and you can stay put while it's built, but the first payments come from the cash and CPF you already have, and the flat has to be sold within six months of getting the keys.
When each payment falls due depends on the payment scheme CDL offers, which it hasn't announced yet: see how the two payment schemes compare. For the general order of selling and buying, see selling first or buying first.
- 4
Get your flat ready to sell
What James does before a flat goes on the market
Check the date your minimum occupation period ends and how much is left on the loan. Look at what nearby flats actually sold for before setting an asking price. Get good photos and be clear about what buyers can check at a viewing. And agree timing that suits your next move, including whether you'll need to stay on after completion: HDB allows a temporary extension of stay only for sellers who have bought a completed home.
More on completion timing and staying on: resale completion or extension of stay. For the Woodlands resale market as a whole: the Woodlands HDB resale market.
- 5
One family's move, for context
Their situation, not a formula
James helped one family move from 635B Senja Road to Copen Grand, an EC, timing the sale and a bridging loan together. The 635B case tells the story. It was an exceptional case that rested on that family's own bank, buyer and dates; another family, or another launch, may not get the same financing, timeline or approvals.
- 6
Back to Wynwood Grand
Where it is, and who can buy
What living there would be like: Wynwood Grand at Woodlands Drive 17. What's open around it and what's still to come: Woodlands' plans and Wynwood Grand. Who can buy an EC: the EC eligibility guide. And if you're comparing launches, Solano Grand is on the same EC rules.
Official rules
Key rules and policies
Disposal of an HDB flat
Anyone listed who owns an HDB flat must dispose of it within 6 months of collecting the EC's keys, based on the legal completion date of the disposal.
Last verified 20 Oct 2026
Source: Conditions After Buying an Executive Condominium (Housing & Development Board), Last updated 28 Jul 2026. Extracted 20 Oct 2026.
Loan limits
With no outstanding housing loan, a bank may lend up to 75% (at least 5% in cash), or 55% if the tenure is over 30 years or runs past age 65. With one outstanding housing loan: 45% or 25%, with at least 25% in cash.
Last verified 20 Oct 2026
Source: Rules for new housing loans (Monetary Authority of Singapore), LTV limits for options granted on or after 6 Jul 2018. Extracted 20 Oct 2026.
Worked scenarios
Illustrations based on the stated assumptions, not forecasts.
What a sale leaves (assumed figures, not 710's)
Assumptions
- Sale price
- $560,000
- Outstanding loan
- $120,000
- CPF returned with accrued interest
- $210,000
- Costs
- $10,000
Result
- Cash left
- $220,000
- In your CPF account
- $210,000
Illustrative figures to show the order of deductions. Use your own loan statement and CPF Board's figures.
Common mistakes
- Treating an asking price, yours or a neighbour's, as what a flat will sell for.
- Counting the CPF refund as cash, or forgetting the resale levy.
- Booking first without checking you can make the first payments before the sale.
- Planning the sale around the launch date instead of the EC's keys.
Questions to ask your bank, lawyer or agent
- 1.My bank: what will it lend for the EC with my flat's loan still outstanding, and after it is repaid?
- 2.CPF Board: how much will go back to my CPF account when the flat is sold?
- 3.James: what could my flat sell for, and which order of selling and buying suits my family?
Seen in practice
Case studies and videos where this decision came up.
Case study
635B Senja Road to Copen Grand: buying an EC while still living in the HDB flat
Step 1: Challenge
So the sale had to meet the bridging loan's timeline, while the family still needed somewhere to live until Copen Grand was ready.
Step 2: Strategy
The bridging loan's timeline set when the flat had to be sold.
Step 3: Result
The flat was sold for S$642,000.
Read the case study
Frequently asked questions
Can I book Wynwood Grand before selling my HDB flat?
Yes. HDB gives you six months from getting the EC's keys to sell your flat. Check with your bank how much it will lend while your flat's loan is still there.
Is 710 Woodlands Drive 70 linked to Wynwood Grand?
No. It's a flat James is selling, used here as an example of pricing a Woodlands flat from what nearby flats sold for.
Limitations
The example figures are assumed, not 710 Woodlands Drive 70's. An asking price is not a valuation or a sale. Your bank, HDB and CPF Board decide your own figures.
Sources
- 1.Conditions After Buying an Executive Condominium
Housing & Development Board · Period: Last updated 28 Jul 2026 · Extracted 20 Oct 2026
Disposal of an HDB flat within 6 months of the EC's key collection.
- 2.Sales proceeds after selling your home
CPF Board · Period: Last updated 30 Nov 2025 · Extracted 20 Oct 2026
Refund of CPF with accrued interest; usable for the next home.
- 3.Rules for new housing loans
Monetary Authority of Singapore · Period: LTV limits for options granted on or after 6 Jul 2018 · Extracted 20 Oct 2026
Loan-to-value limits with an outstanding housing loan.
- 4.MAS Notice 632: Residential Property Loans
Monetary Authority of Singapore · Period: Version last revised 21 Aug 2025 · Extracted 20 Oct 2026
Paragraphs 8 and 9: when an existing loan is left out.
- 5.1H 2026 Results Presentation
City Developments Limited · Period: Presented 13 Aug 2026 · Extracted 20 Oct 2026
Wynwood Grand: targeted launch Q1 2027.
Wong Say Tian (James) · CEA Reg. No. R007728G · +65 9696 9567 · PropNex Realty Pte Ltd · Licence No. L3008022J
General information only, not financial, legal or tax advice. Figures reflect the data period shown and may since have changed; your own circumstances will differ. Full disclaimer.
Continue exploring
For sale· Photos on TikTok
710 Woodlands Drive 70: 4-room Model A flat, 101 sq m
3 bedrooms and 2 bathrooms · Separate service yard
$588,000
View property
Related analysis
HDB · Woodlands
710 Woodlands Drive 70 at S$588,000: How I Would Assess This 101 sq m 4-Room Flat
A buyer-focused assessment of a 101 sq m 4-room Model A at 710 Woodlands Drive 70 asking S$588,000, including Woodlands resale context, size, lease, location and trade-offs.
Talk to James
Your move to Wynwood starts with your current flat.
Tell James which flat you own and when you'd like to move. He'll go through what it could sell for based on real sales nearby, what you'd walk away with after the loan and CPF refund, and the order to sell and buy in. Please do not send NRIC, income, CPF or bank documents through the form or WhatsApp.
Your WhatsApp message will read: “Hi James, I read "Own a Woodlands HDB…" on JamesWongHomes.com and would like to discuss selling my Woodlands flat. [woodlands-hdb-owners-wynwood-grand-sell-your-flat-first-steps]” Edit it before you send.
Prefer to call? +65 9696 9567
I usually reply within one working day.
Messages go directly to James. Your details are used only to respond to your enquiry. See the privacy notice.